Chancellor boosts share option schemes for businesses
The expansion of tax-advantaged share options could significantly aid businesses in employee retention and attraction
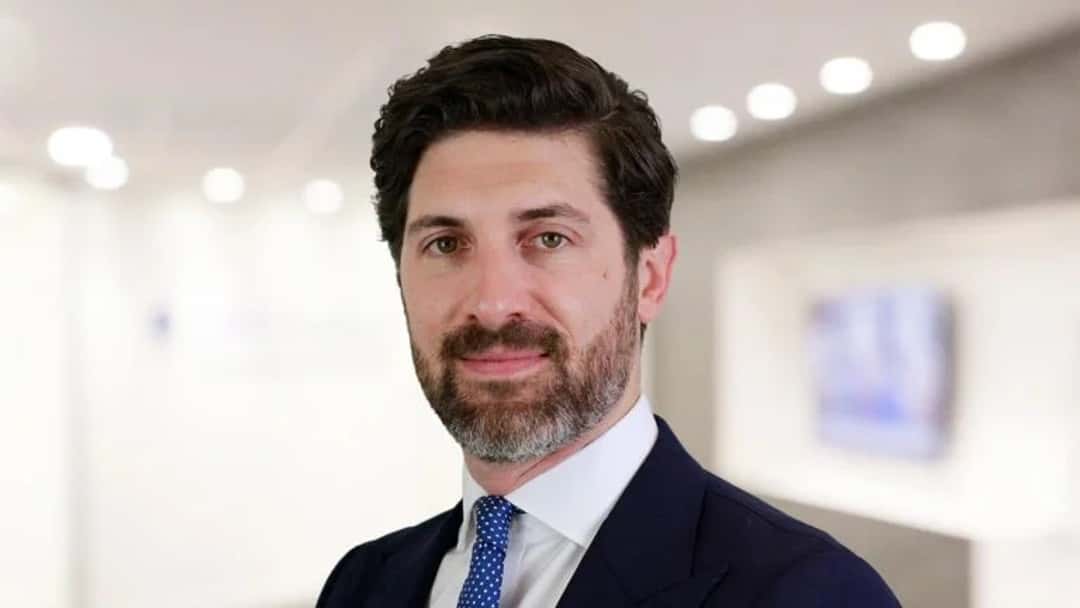
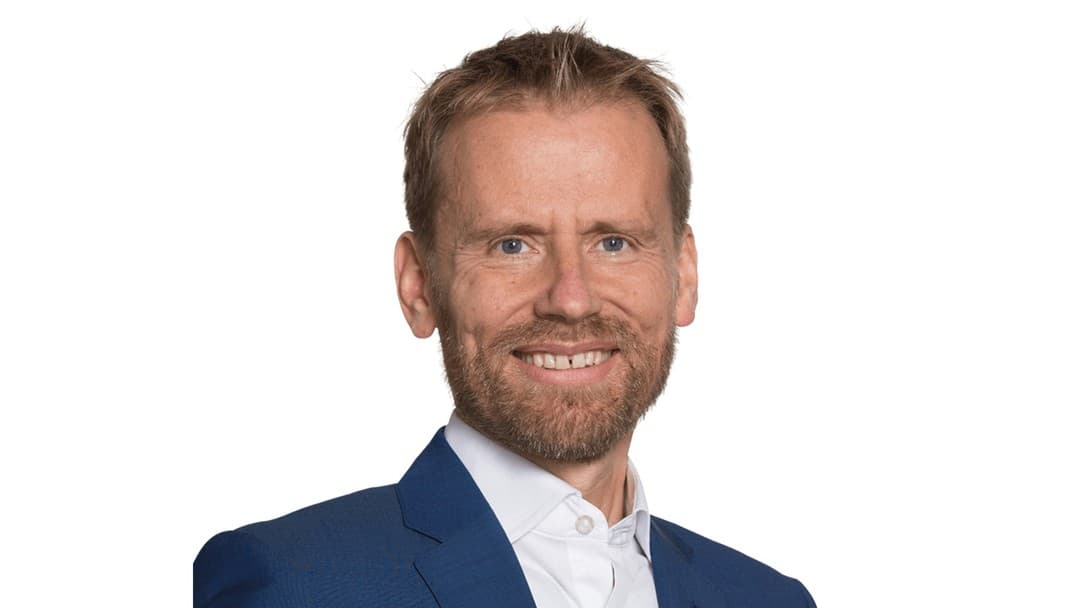
In a recent announcement, Michael Carter, Partner and Head of Incentives at Osborne Clarke, expressed his enthusiasm for the expansion of tax-advantaged share options introduced by the Chancellor. He remarked, “The Chancellor has given businesses a welcome boost in their efforts to attract and retain employees by expanding the tax advantages available through share option schemes.” Following last year's modifications to the Enterprise Management Incentives (EMI), the Chancellor's latest initiative aims to rename the Company Share Option Plan (CSOP) as EMI2, with enhanced limits set to take effect from April 2027.
These changes are set to allow employees to obtain up to £370,000 in tax-advantaged share options across both schemes, provided they meet the necessary eligibility criteria. For burgeoning businesses, offering share options is vital as it incentivises employees and fosters a sense of ownership in the company's long-term success. Michael noted, “This is a positive development for businesses looking to incentivise their people, although the detail of the new EMI2 rules will be important in determining how widely the benefits can be used.”
As the government rolls out these changes, it is clear that they see enhancing share option schemes as a strategic measure to help businesses thrive amidst economic uncertainties, especially in a competitive talent market. The measure holds promise for many firms seeking alternatives to traditional salary packages while promoting loyalty and motivation among employees.
As businesses adapt to the evolving landscape, the ramifications of these reforms will surely be closely examined in the months leading up to the full implementation of EMI2 in April 2027
 Copyright & permissions