This briefing draws on the September 2026 webinar Delivering Clean Energy Through the Planning System, presented by Rob Shaw of Third Revolution Projects with Odette Chalaby of Landmark Chambers and Martyn Jarvis of Town Legal.
For project developers, the new NPPF provides a materially stronger starting point for renewable and low-carbon energy projects, including repowering. At the same time, grid constraint and connections reform are changing project economics and encouraging new models around co-location, private wire, microgrids and integrated generation projects with data centres and industrial uses.
For planners and economic-development teams, the implication is that energy infrastructure can no longer be treated as something to resolve after land-use decisions are made. Grid capacity, generation, storage and demand increasingly need to inform spatial strategy, allocations and the deliverability of housing, industry and data-centre growth.
For existing assets, the opportunity is to look again at existing sites and portfolios through a wider development lens. Land, planning history, grid access and infrastructure may combine to support higher-value uses, additional generation, storage, private networks or co-located demand. For both asset owners and developers, the key question is increasingly: what combination of land, energy, infrastructure and demand creates the most valuable and deliverable project?
The full webinar can be viewed here
A significantly more positive starting point for clean energy
The August 2026 National Planning Policy Framework marks an important change in the planning context for renewable and low-carbon energy development in England.
The new Chapter 10, Securing clean energy and water, gives substantially greater prominence to both clean-energy generation and the electricity infrastructure needed to support it. The change both strengthens the position of individual projects coming forward, while also requiring the planning system to take a much more active role in identifying where future energy infrastructure should go and how it relates to housing and industry.
For applications, Policy W3 provides a notably positive starting point. Substantial weight is to be given individually to the benefits of renewable and low-carbon energy and electricity network infrastructure for energy security, economic development and the transition to net zero. Repowering and life-extension proposals receive specific recognition of the additional benefit of using an established site. As previously, applicants should not be required to demonstrate a need for renewable or low-carbon energy development or electricity network infrastructure. Importantly, being outside an area identified as suitable in the development plan is not, in itself, a reason for rejection: the proposal is instead assessed against the national decision-making policies as a whole.
That sits alongside the new presumption in favour of approval for particular forms of development, including outside settlements. Energy infrastructure is expressly included within Policy S5, under which qualifying proposals should be approved unless their benefits are substantially outweighed by adverse effects when assessed against the national decision-making policies or where policies indicate refusal. Green Belt has its own regime, but the Framework also provides a similar balance where development is not inappropriate in the Green Belt (including Grey Belt).
There is a further important transitional point. From publication of the new Framework, development-plan policies that are materially inconsistent with the new national decision-making policies should be given very limited weight, unless they were examined and adopted against the new Framework. That will require careful consideration in areas where older local energy policies are significantly less supportive than the national position now is.
None of this creates an automatic route to consent. Landscape, heritage, ecology, flood risk, Green Belt and other constraints all matter, and the national policies contain circumstances in which adverse effects can outweigh benefits. But for well-conceived renewable and low-carbon energy schemes, the positive side of the planning balance has strengthened materially.
For developers with new projects, consented schemes that need amendment, or projects that stalled under an earlier planning and commercial context, that makes this a good time to reconsider the planning position.
Policy has changed at the same time as the market
The timing is important because the energy development market is itself changing.
For much of the last two decades, the development model was relatively linear: secure grid, identify land, obtain planning permission, construct generation and export power to the network. That model remains essential as Britain still needs a substantial pipeline of deliverable generation, but it is no longer the whole picture.
Grid capacity has become both scarce and strategic.
Generation connections reform illustrates that shift. Under the reformed process, projects meeting Gate 2 readiness and strategic-alignment requirements can secure a confirmed connection point, date and queue position. Grid access is therefore increasingly connected to whether a project is genuinely ready and whether it fits the future energy system, rather than simply its historic place in a queue.
The same pressures are now evident on the demand side. Ofgem's July proposals respond particularly to rapid growth in data-centre applications and would introduce a hefty non-refundable commitment fee for demand over 40MW and additional milestones intended to remove non-viable projects and prioritise credible ones. The consultation closed in September and a decision is awaited.
For both generators and high-energy users, the implications extend beyond connection administration. Where grid capacity exists, or where generation, demand and infrastructure can be brought together, increasingly influences the commercial value and deliverability of development locations.
We need more clean supply, and more productive demand
At the same time, electrification means Britain needs substantially more electricity demand as well as more supply.
Decarbonising transport, heat and industry means replacing fossil-fuel energy with electricity. Economic growth adds further demand, including from digital infrastructure and data centres. Delivering that requires more renewable generation, storage, networks and increasingly sophisticated ways of balancing supply and demand.
The planning challenge should therefore not simply be framed as accommodating individual energy projects on one side and controlling major electricity demand on the other. It is increasingly about bringing clean generation, network capacity and productive demand together in the right locations.
The new NPPF explicitly moves in this direction. Policy W2 requires positive planning for greater renewable and low-carbon energy supply and network infrastructure, including identifying suitable areas and looking for opportunities for development to draw energy from decentralised systems and to co-locate suppliers and customers of energy or surplus heat.
The economic policies reinforce the point. Policy E2 recognises that electricity infrastructure can give particular locations strategic importance and expressly refers to opportunities to co-locate large-scale generators with major users of power, including data centres.
That is significant. Energy infrastructure is becoming part of the spatial rationale for economic development, rather than something dealt with after a site has been selected.
New development models are emerging
We are already seeing the market respond. Across TRP's work, four models are becoming particularly relevant:
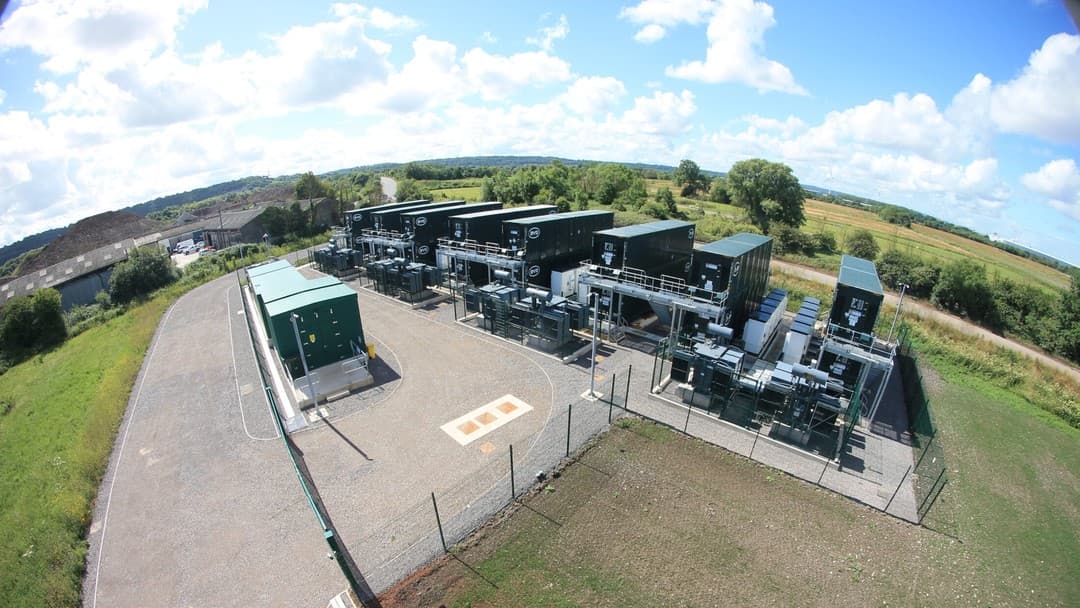
Co-location of generation and storage, making better use of land and grid capacity.
Private wire, connecting generation directly to existing industrial and other high-energy users.
Microgrids and integrated energy-led development, bringing generation, storage and new demand, including data centres, industry and potentially major housing development, into a single system.
Repowering and re-use, extracting greater value from established renewable sites, consents and infrastructure.
Sometimes these models are a response to grid constraint: enabling development to reduce its dependence on the public network or to progress differently while reinforcement is awaited.
But the opportunity is broader. Electrification, energy costs and the value of secure access to power can make integrated projects commercially attractive in their own right.
The distinction between an energy project and an economic-development project consequently becomes less clear. A data-centre campus may incorporate significant generation and storage. An industrial site may require a private renewable network to make electrification viable. A renewable project may create the infrastructure around which future economic development becomes attractive.
This is likely to change both the types of planning applications authorities receive and how projects need to be conceived from the outset.
Existing energy assets may be development assets too
One of the most interesting consequences is the potential to look differently at existing renewable portfolios.
Many operational renewable assets were designed in a very different market. The planning permission, land agreement, technology and grid connection were all structured around the commercial proposition available at the time.
Today, the context is different. Grid rights are scarce. Battery storage is mainstream. High-energy demand is growing. Private networks and microgrids are increasingly relevant.
Operators will already be looking at conventional optimisation through repowering, extensions and storage. But there is a wider question.
An operational renewable site may also represent a development location with a valuable combination of land, established planning history, grid access and energy infrastructure.
That changes a developer’s question from “how can we maximise generation from this asset?” to “what is now the highest-value and most deliverable future use of the combination of assets we have here?”. For plan-making, the related question might be “how could these assets unlock strategic development or our spatial strategy?”
In some locations the answer will remain additional or improved generation. Elsewhere there may be opportunities for storage, private networks or co-located industrial, data-centre or other demand. Conversely, concentrations of existing high-energy users may provide an opportunity to originate new generation and infrastructure around them.
For asset owners, this suggests value in reviewing portfolios not simply as collections of generating assets but as potential development portfolios.
Planning strategy needs to start earlier
The NPPF's plan-making changes are just as important as the decision-taking policies.
Policy W1 expects development plans to be informed by early engagement with utilities, regulators and network operators so that authorities understand energy supply, network capacity and future infrastructure needs. Policy W2 then requires positive planning for increased renewable generation and network infrastructure.
At strategic level, spatial development strategies are expected to identify the broad location and extent of infrastructure needed to enable future growth, explicitly including renewable and low-carbon energy and electricity networks.
At the same time, NESO is developing the Strategic Spatial Energy Plan for Great Britain and Regional Energy Strategic Plans intended to bring a more joined-up approach to future energy infrastructure.
Over time, these processes should combine: land-use plans identifying where growth is intended, and energy-system plans identifying what energy infrastructure is required and where it can best be provided.
For developers, that means engagement in plan-making may become as important as the strategy for an individual planning application. Securing the right allocation, infrastructure recognition or strategic alignment could materially affect future project deliverability and value.
More flexibility is also emerging around delivery
There are further changes that could help integrated projects. Data centres can now, where the statutory tests are satisfied and the Secretary of State considers the project nationally significant, be directed into the NSIP regime; conversely, new powers allow qualifying NSIP development to be directed to an alternative consenting route where appropriate.
Ofgem's Connect Accelerate work is also examining greater rights to self-build and own, or self-build and transfer, high-voltage assets, potentially creating new routes for major demand, generation and storage projects to take greater control over connection delivery. These reforms remain under development.
Integrated developments also need careful consideration of what constitutes the overall project for environmental assessment purposes: generation, demand and associated connection infrastructure cannot necessarily be treated as entirely separate merely because they sit within separate applications. That was one of the legal issues highlighted in the webinar.
What does this mean for projects now?
There are two parallel opportunities.
The first is straightforward: continue to bring forward good renewable and low-carbon energy projects. National policy now gives them a materially stronger starting point, including repowering and projects outside areas previously identified for renewable development.
The second is to look more broadly at energy, land and demand together. Existing renewable portfolios, stalled projects, land with grid capacity, data-centre sites and industrial locations may contain development opportunities that were not apparent when they were first assembled.
For developers and asset owners, the question is increasingly not simply “can this project obtain planning permission?” but “what combination of land, energy, infrastructure and demand gives this location its greatest future opportunity and what planning strategy is needed to unlock it?”
For planners and political leaders, the types of project coming forward will change, with more colocation of technologies and uses, and more repowering. So, energy infrastructure needs to be treated as fundamental to economic development, spatial strategy and to whether plans for housing and industry are actually deliverable.



 Copyright & permissions